Imagine a company that sells you equipment, invests money in your business, and then rents back what you build with it. It’s your supplier, your investor and your customer all at once.
That’s known as circular financing.
Many artificial intelligence (AI) companies, including Microsoft, Amazon, Google and Nvidia, have adopted a version of this opaque method of financing.
A chip supplier invests in a customer such as a data centre builder, the customer spends the money on the supplier’s chips, and both companies report growth.
One central bank analysis found that 55.2% of investments into AI firms came from other AI firms.
What’s not clear to investors or the market is how much of this AI boom is being driven by real, end-user demand — and how much might be a bubble.
It all comes back to Nvidia
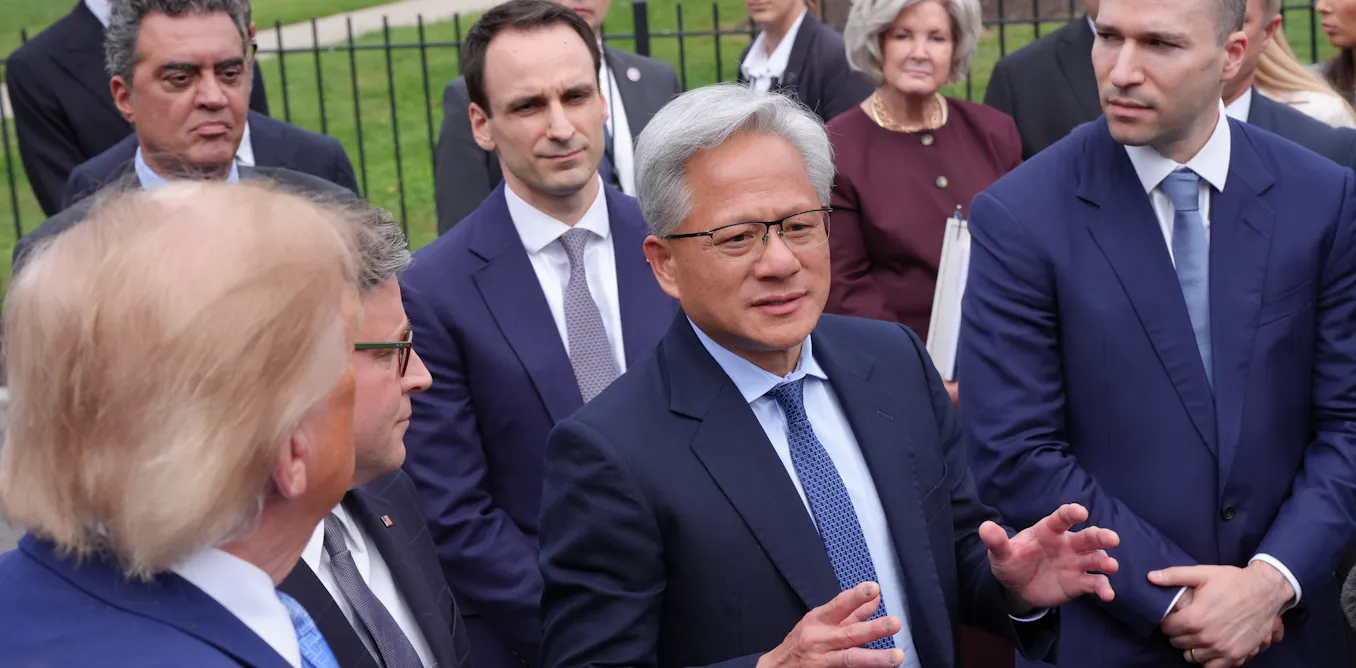
Take Nvidia. The world’s leading chipmaker is investing in ChatGPT owner OpenAI to support data centres filled with Nvidia chips.
Nvidia will invest US$30 billion in a private funding round in OpenAI and provide a guarantee of up to US$105 billion for an OpenAI data centre in Ohio, as well as investing in the company building it.
That helps OpenAI to remain Nvidia’s best customer, but it also raises the question: is the chipmaker propping up the market?
Nvidia has invested in other AI firms as well, including up to US$10 billion in Anthropic, the developer of Claude.
It bought US$2 billion of shares in cloud provider CoreWeave to help it speed up the build-out of AI factories that use Nvidia technology.
In total, Nvidia made more than 50 different investment deals in AI companies in 2024 alone.
Some of those deals are staged over years or still open-ended. But these circular deals help the AI build-out move faster than it could without Nvidia’s financing.
The Australian story – Firmus
Data centre builder Firmus – which last week dramatically abandoned plans to list on the Australian Securities Exchange – provides the local example. Nvidia wears all three hats for Firmus:
Supplied
-
Investor: Nvidia first invested in Firmus Technologies through the company’s A$330 million capital raising in September 2025 to finance data centres in Tasmania. It then participated as an existing investor in two further funding rounds, one in April 2026 and Firmus’s US$2 billion funding round in August 2026. Nvidia did not disclose how much it invested.
-
Supplier: Firmus plans to build data centres using Nvidia’s DSX AI factory platform, which combines chips, networking and software to provide computing capacity
-
Customer: Firmus signed Nvidia as a customer for its data centre in Batam, Indonesia, worth up to US$30 billion over six years. Meanwhile, Open AI (with its existing relationship with Nvidia) has been named as an anchor customer at Firmus’s Malaysian data centres.
These circular deals also concentrate risk
The same loop concentrates risk. With Nvidia acting as investor, supplier and financier across the AI sector, trouble at one firm can spread quickly to the others. It also complicates valuations.
For instance, OpenAI’s method of reporting revenues has been queried. Its shares were hit last week when the Financial Times reported its annualised revenues were US$20 billion less than the company had suggested.
The Reserve Bank of Australia warned in its recent Financial Stability Review that there are “pockets” of higher-risk companies, including those using opaque or circular funding arrangements, where chipmakers provide financing to the companies that purchase their products.
Warning about the possibility of the AI bubble bursting, the RBA said:
One possible trigger could be a shift in sentiment towards the AI investment boom, which is increasingly fuelled by expectations of sustained rapid earnings growth and a debt-financing cycle that is becoming more opaque and circular.
The concern is that nearly all the gains in the US stockmarket have been driven by AI companies.
On Wall Street, chipmakers have contributed around 70% of the total gains in 2026 for the S&P 500, and Nvidia is now the index’s largest single company at about 8.06% of the index.
This makes the market fragile. If investors begin doubting that OpenAI and similar customers can earn enough in revenue from customers to meet their commitments, Nvidia would be hit on two fronts. First, via lower expected sales and second via its financing exposure to those same companies. That would drag down the whole market, due to its heavy weighting in the key index.
Australians would feel it too. Nearly 90% of households are exposed to AI stocks, due to the US shares held through their superannuation funds.
A question of timing
None of this means the AI boom is fake. The issue is timing.
Nvidia, OpenAI and Firmus are betting that future revenue from users and businesses will grow fast enough to pay for today’s massive data centre build-out. Until then, investors, lenders and each other’s companies fill the financing gap.
There is a historical comparison with the 1990s telecom boom. In what was then called the “New Economy”, equipment makers such as Cisco Systems financed customers to buy their equipment. Too much fibre was laid too soon, and investors lost heavily when the stock market bubble burst.
But that fibre lasted decades. The newest AI chips have a shelf life of only a few years. If the expected revenue and demand from business and consumers arrives late or below forecasts, shareholders and super funds will bear the losses.
The post “Who’s paying whom? The circular money machine behind the AI boom (or bubble)” by Ruipeng Liu, Senior Lecturer in finance, Deakin University was published on 10/13/2026 by theconversation.com